You receive your salary. Rent or EMI gets paid. Groceries are bought. School fees arrive. A few UPI payments here and there don’t seem like much.
Then, somewhere around the third week of the month, you start wondering:
Where did all the money go?
This is where a family budget method can help.
A family budget is not about stopping your family from enjoying life. It is about deciding where your money should go before the month begins, instead of trying to figure it out after the money is already gone.
For an Indian family, budgeting also needs to account for things that don’t happen every month — school expenses, insurance premiums, festivals, vehicle servicing, medical expenses, family functions and unexpected repairs.
This guide uses a simple 5-Bucket Family Budget Method that you can adapt to your own income and circumstances.
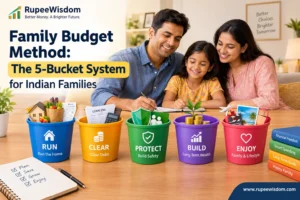
The RupeeWisdom 5-Bucket Family Budget Method
Think of your household income as money that has five main jobs:
1. RUN — Run the Home
Money needed for your family’s basic day-to-day life.
2. CLEAR — Clear Debt
Money committed to EMIs and other debt repayment.
3. PROTECT — Build Financial Safety
Money for your emergency fund and appropriate insurance protection.
4. BUILD — Build Long-Term Wealth
Money for investments and long-term financial goals.
5. ENJOY — Enjoy Your Money
Money for eating out, shopping, entertainment, hobbies and family activities.
Remember it as:
RUN → CLEAR → PROTECT → BUILD → ENJOY
There is no perfect percentage that every Indian family needs to follow.
The important thing is that every major part of your financial life has a place in the budget.
Before You Make a Family Budget, Check Your Actual Spending
Don’t start by guessing.
Look at the last two or three months of:
- Bank statements
- UPI transactions
- Credit-card statements
- Cash spending
- Electricity and gas bills
- Grocery purchases
- School-related expenses
- Loan and EMI payments
You may discover that the number in your head is very different from the number in your bank account.
Perhaps you thought you spent ₹6,000 on groceries but actually spent ₹8,500.
Perhaps you forgot about several annual payments.
Perhaps small UPI transactions are adding up to several thousand rupees a month.
Your past spending gives you a starting point based on reality rather than hope.
Bucket 1: RUN — Run the Home
This is the money required to keep your household running.
It can include:
- Rent
- Home-loan-related household costs
- Groceries
- Electricity
- LPG
- Water
- Society maintenance
- Mobile and internet
- School expenses
- Transportation
- Domestic help
- Basic medical expenses
- Other necessary household costs
These are your core expenses.
You should know approximately how much your family needs to run the household each month.
Fixed vs Variable Expenses
It is useful to divide your expenses into two broad groups.
Fixed expenses are relatively predictable:
- Rent
- EMI
- School fees
- Insurance premiums
- Internet
- Some subscriptions
Variable expenses change from month to month:
- Groceries
- Electricity
- Fuel
- Medicines
- Eating out
- Shopping
Fixed expenses are generally easier to predict but may be harder to change quickly.
Variable expenses can be easier to adjust, but they need more attention because they can gradually creep upward.
If your essential expenses are already consuming most of your income, don’t ignore the problem.
It may mean that your housing, transportation, debt or other fixed costs are too high for your current income.
Bucket 2: CLEAR — Clear Debt
If your family has debt, give it its own place in the budget.
Include:
- Personal-loan EMIs
- Home-loan EMIs
- Vehicle loans
- Education loans
- Credit-card payments
- Other regular debt obligations
Debt can quietly consume a large part of household income.
For example, a family earning ₹70,000 per month may appear financially comfortable until you discover that ₹25,000 is already committed to loan payments.
That changes the picture completely.
If you have expensive debt, reducing it may sometimes be more useful than aggressively increasing investments.
The right balance depends on the interest rate, emergency savings, financial goals and your overall situation.
Bucket 3: PROTECT — Build Financial Safety
This bucket is about protecting your family from financial shocks.
It can include:
- Emergency fund
- Health insurance
- Life insurance where appropriate
- Short-term savings for known needs
An emergency fund is important because family expenses don’t always follow your monthly budget.
A medical problem, job loss, major repair or other unexpected event can put pressure on your finances very quickly.
You don’t have to build a huge emergency fund immediately.
Start with a realistic target and build it gradually.
If you’re starting from zero, see our guide on how to save for an emergency fund in India for a practical step-by-step approach.
Bucket 4: BUILD — Build Long-Term Wealth
Once your basic financial foundation is in place, allocate money towards long-term goals.
Depending on your circumstances, this could include:
- EPF
- PPF
- Mutual fund SIPs
- Other long-term investments
- Retirement savings
- Children’s future education
- Other financial goals
The exact investment products you choose should depend on your goals, time horizon, risk tolerance and circumstances.
If you’re new to mutual funds, our beginner’s guide to what a mutual fund is explains how mutual funds work, what you actually own and how SIPs fit into the picture.
The budgeting principle is simpler:
Don’t leave long-term savings to whatever happens to remain at the end of the month.
If you wait until the end, there may be nothing left.
Bucket 5: ENJOY — Enjoy Your Money
This bucket is often forgotten.
It shouldn’t be.
Your family may want to:
- Eat out
- Watch a movie
- Buy clothes
- Take a small trip
- Celebrate birthdays
- Pursue hobbies
- Buy something you’ve wanted
These expenses aren’t automatically bad.
A budget that allows absolutely no enjoyment can become so restrictive that the family eventually stops following it.
Instead, decide how much you can comfortably spend on flexible expenses.
Then enjoy that money without feeling guilty.
A Practical Family Budget Example: ₹60,000 a Month
Let’s say a family has a combined take-home income of ₹60,000 per month.
Here is one possible example:
| Budget Bucket | Example Monthly Amount |
|---|---|
| RUN — Run the Home | ₹33,000 |
| CLEAR — Clear Debt | ₹7,000 |
| PROTECT — Build Safety | ₹4,000 |
| BUILD — Build Wealth | ₹7,000 |
| ENJOY — Flexible Spending | ₹6,000 |
| Monthly Buffer | ₹3,000 |
| Total | ₹60,000 |
Important: This is an illustrative example, not a recommended percentage allocation.
A family paying ₹20,000 in rent will have a different budget from a family living in its own home.
A family with two children may spend more on education. A family supporting elderly parents may have higher medical expenses.
The purpose is to understand the structure, not to copy these exact numbers.
Notice something important about this budget.
The family has not eliminated flexible spending. At the same time, money is being deliberately allocated to debt, financial safety and long-term wealth.
That makes the budget more realistic than simply saying:
“Save 20% of your income.”
A Realistic Indian Family Example
Let’s take a fictional example.
Amit earns ₹52,000 a month and his wife earns ₹28,000. Their combined take-home income is ₹80,000.
They have one child, pay ₹14,000 rent and have a ₹7,500 personal-loan EMI. They also regularly help Amit’s parents financially.
Without a budget, they may simply use the ₹80,000 as one large pool of money.
The problem is that several different priorities are competing for the same money.
Using the five buckets, they could first identify:
RUN: rent, groceries, school expenses, electricity, transport and other household needs.
CLEAR: the ₹7,500 loan EMI and a plan for additional debt repayment if affordable.
PROTECT: emergency savings and appropriate insurance.
BUILD: long-term investments and retirement savings.
ENJOY: family outings, shopping and other discretionary expenses.
The exact amounts would depend on their actual spending.
The important change is that the couple now knows what each rupee is supposed to do.
That’s the real purpose of a budget.
A One-Page Family Budget Template
You can start with something as simple as this:
| Your Money | Monthly Amount |
|---|---|
| Take-home household income | ₹ |
| RUN — Essential household expenses | ₹ |
| CLEAR — Debt payments | ₹ |
| PROTECT — Emergency & protection | ₹ |
| BUILD — Savings & investments | ₹ |
| ENJOY — Flexible spending | ₹ |
| Monthly buffer | ₹ |
| Amount left over | ₹ |
If the final number is negative, don’t hide it.
That’s the first problem your budget needs to solve.
You don’t need an elaborate spreadsheet to get started.
A notebook, spreadsheet or simple budgeting app can be enough.
Where Can Family Money Leak?
Family finances don’t always get damaged by one huge purchase.
Sometimes money leaks through many small decisions.
For example:
- Frequent food delivery
- Unplanned online shopping
- Unused subscriptions
- Repeated small UPI purchases
- Weekend spending
- Convenience fees
- Impulse purchases
- Frequent cash withdrawals
- Credit-card purchases that weren’t planned
But don’t make the mistake of assuming that every small expense is wasteful.
₹200 spent on something your family genuinely enjoys isn’t automatically a problem.
The better question is:
“Is this expense giving us enough value for the money we’re spending?”
The purpose of a budget is not to eliminate every small pleasure.
It is to identify spending that doesn’t matter enough to justify its cost.
Don’t Forget Irregular Expenses
This is one of the most important parts of family budgeting.
Some expenses aren’t monthly, but they are not really unexpected.
For example:
- Annual insurance premiums
- School admission expenses
- Vehicle servicing
- Property tax
- Festival spending
- Family functions
- Home repairs
- Annual subscriptions
- Children’s activities
- Travel
- Gifts
Suppose you expect these expenses to cost approximately ₹36,000 over the year.
Instead of waiting for each bill to arrive, divide the amount by 12.
₹36,000 ÷ 12 = ₹3,000 per month
Set aside ₹3,000 every month.
When the annual expense arrives, the money is already waiting.
If you don’t plan for irregular expenses, they will keep looking like emergencies.
How to Budget on Salary Day
For salaried families, one of the easiest ways to make a budget work is to make your major allocations when the salary arrives.
For example:
Salary received
↓
Set aside savings
↓
Allocate essential expenses
↓
Keep debt payments ready
↓
Set aside money for annual expenses
↓
Leave the planned amount for flexible spending
The idea is simple:
Don’t wait until the end of the month to see whether you can save.
Give important financial goals their money first.
This does not mean you should blindly maximise savings while ignoring essential expenses. Your allocations still need to be realistic.
Don’t Budget From CTC
This is particularly important for salaried employees in India.
Your CTC is not the same as the money you can spend every month.
There can be a difference between:
CTC → Gross Salary → Deductions → Take-Home Salary
Your family budget should generally be based on the amount that actually becomes available for household spending, not simply the CTC shown in your employment package.
If you budget from a number that never reaches your bank account, your budget is wrong before you start.
What If Your Family Income Changes Every Month?
This is common for business owners, freelancers, commission-based workers and self-employed people.
The biggest mistake is to build your lifestyle around your best month.
Suppose your household income is:
| Month | Income |
|---|---|
| January | ₹65,000 |
| February | ₹52,000 |
| March | ₹82,000 |
| April | ₹57,000 |
It would be risky to create permanent monthly expenses based on ₹82,000.
Instead, use a conservative income figure for your regular budget.
When you have a better month, you can direct the additional money towards:
- Emergency savings
- Debt repayment
- Investments
- Upcoming annual expenses
- Specific financial goals
This helps prevent lifestyle expenses from rising every time income rises.
What If Your Family Budget Is Already in the Red?
This is where many budgeting articles become unrealistic.
Suppose your household income is ₹50,000.
Your essential expenses are ₹38,000.
Your EMIs are ₹15,000.
You are already at ₹53,000 before saving anything.
Telling this family to “save 20% every month” isn’t particularly helpful.
First, understand the problem.
Separate Needs From Wants
Look at your expenses and identify what can actually be reduced.
You may discover that some costs are flexible while others aren’t.
Review Your Debt
List every loan and credit-card balance along with the EMI, outstanding amount and interest rate if known.
Don’t take new loans simply to continue paying for routine expenses.
Look at Fixed Costs
Rent, transportation and debt payments can have a much larger impact than cutting a few small purchases.
Focus on the expenses that can genuinely change the financial picture.
Look at Income Too
A family budget isn’t only about cutting expenses.
If expenses have reached the practical minimum, increasing income may be the more realistic solution.
Don’t Hide the Problem
If debt has become unmanageable, don’t pretend it is merely a budgeting issue.
Budgeting can help you understand the problem, but serious debt may require a separate repayment or debt-resolution strategy.
Stress-Test Your Family Budget
Before you finalise your budget, ask yourself a few uncomfortable questions.
What happens if my income stops for three months?
What happens if the car needs a ₹20,000 repair?
What happens if school expenses suddenly increase?
What happens if a family member has a medical expense?
You don’t need perfect answers.
But if one unexpected bill can completely destroy your budget, it tells you something important about your emergency savings and financial commitments.
A good budget isn’t only designed for a normal month.
It should also help your family prepare for a bad month.
How to Make a Family Budget in 30 Minutes
You don’t need an elaborate spreadsheet.
Start with these steps.
Step 1: Write Down Your Monthly Take-Home Income
Use the money that actually reaches your bank account.
Don’t use CTC as your monthly spendable income.
Step 2: List Your Essential Expenses
Write down rent, groceries, utilities, school expenses, transportation and other necessary household costs.
Step 3: List Your Debt Payments
Write down every EMI and regular debt payment separately.
Step 4: Decide Your Safety and Savings Amount
Choose realistic amounts for your emergency fund and long-term investments.
Step 5: Add Irregular Expenses
Look at your expected annual expenses and divide them by 12.
Step 6: Set Your Flexible Spending Limit
Decide how much your family can comfortably spend on non-essential things.
Step 7: Keep a Small Buffer
Don’t make the budget so tight that one slightly higher electricity bill destroys it.
A small monthly buffer can make the system much easier to follow.
How Couples Can Manage a Family Budget
A family budget works better when both partners understand the financial picture.
You don’t necessarily need to put every rupee into a joint account.
You can have separate accounts, a joint account or a combination.
What matters is that both partners know:
- Household income
- Major expenses
- Outstanding loans
- Savings
- Investments
- Upcoming large expenses
A short monthly discussion can be enough.
Ask:
What came in?
What went out?
What is coming up?
What should we change next month?
It doesn’t have to become a two-hour financial meeting.
Budget Priorities Can Change With Your Family Situation
There is no single budget that works for every household.
| Family Situation | Possible Priority |
|---|---|
| Single-income family | Emergency fund and financial protection |
| Dual-income family | Avoiding lifestyle inflation and building wealth |
| Young couple | Emergency fund, debt and future goals |
| Family with children | Education, protection and long-term goals |
| Family supporting parents | Medical and emergency planning |
| High-debt family | Cash-flow control and debt reduction |
These are starting points, not rules.
Your actual priorities depend on your income, expenses, debt, responsibilities and financial goals.
Should You Follow the 50/30/20 Rule?
The 50/30/20 rule is a popular budgeting method.
It generally suggests:
- 50% for needs
- 30% for wants
- 20% for savings and debt repayment
It can be a useful starting point.
But don’t treat it as a rule that every Indian family must follow.
A family in Mumbai paying high rent may have a very different situation from a family living in a smaller town.
A family paying school fees, supporting parents or dealing with significant debt may not fit neatly into these percentages.
Your budget should fit your life.
The 50/30/20 rule is a tool, not a report card.
Common Family Budget Mistakes
1. Making a Budget Without Checking Actual Spending
If you don’t know what you’re currently spending, your budget may be based on guesses.
Check your recent transactions first.
2. Forgetting Annual Expenses
Insurance, school expenses, vehicle servicing and other yearly costs still need to be paid.
Plan for them monthly.
3. Treating Credit Cards as Extra Income
A credit card is a payment method.
It isn’t additional income.
If you cannot comfortably repay the purchase, it needs to be considered part of your spending or debt.
4. Cutting All Enjoyment
A budget should be sustainable.
Leaving some money for family activities and personal spending can make it easier to stick with the plan.
5. Increasing Expenses Every Time Income Increases
When income rises, consider increasing savings and investments before increasing your lifestyle.
Otherwise, a higher salary may not actually improve your financial position.
6. Ignoring Small Expenses
₹200 may not look important.
But ten such expenses are ₹2,000.
Small expenses don’t need to be eliminated. They simply need to be visible.
Family Budget Checklist
Before starting a new month, ask:
- Have we calculated our actual take-home income?
- Have we listed our fixed expenses?
- Have we estimated our variable expenses?
- Have we allocated all debt payments?
- Have we set aside money for savings?
- Have we planned for annual or irregular expenses?
- Have we set a flexible spending limit?
- Have we kept a small buffer?
- Do both partners understand the major financial commitments?
- Is there any upcoming large expense we haven’t planned for?
If you can answer these questions, you’re already much further ahead than a family that simply spends and hopes everything works out.
A Simple Monthly Family Budget Routine
You don’t need to monitor your budget every day.
A simple monthly routine is enough for many families.
At the beginning of the month
Decide:
- Expected income
- Essential expenses
- Debt payments
- Safety and savings
- Irregular expenses
- Flexible spending
During the month
Spend according to the plan.
If one category is higher than expected, adjust another where possible.
Don’t abandon the entire budget because one expense went wrong.
At the end of the month
Spend 15–20 minutes reviewing it.
Ask:
Where did we overspend?
What unexpected expense appeared?
Did we save what we planned?
What should change next month?
That’s it.
You don’t need a perfect financial system.
You need a system you will actually use.
RupeeWisdom’s Approach to Family Budgeting
We believe a family budget should be practical enough to use in real life.
That means accounting for irregular expenses, debt, family responsibilities and some discretionary spending instead of assuming every household fits a fixed budgeting formula.
A good budget should help you understand your financial position, make better decisions and prepare for what may happen next.
For broader guidance on managing money and understanding financial products, readers can also explore the Reserve Bank of India’s financial education resources.
It should not make you feel guilty about every rupee you spend.
A Family Budget Is a Living Plan
Your family budget will change.
Your children may enter a new school. Your rent may increase. You may get a salary increase. A loan may end. Your parents may need additional support. Your family may move to another city.
So don’t create a budget once and forget about it.
Review it periodically.
When something important changes in your life, change the budget with it.
The purpose of budgeting isn’t to predict the future perfectly.
It is to give your family a clear financial direction.
Frequently Asked Questions
What is the best family budget method?
There is no single method that works for every family. A simple system that separates essential expenses, debt, financial safety, long-term wealth and flexible spending can be a practical starting point.
How much should a family save every month?
There is no universal amount. The right figure depends on income, expenses, debt, emergency savings and financial goals. Start with an amount that is realistic enough to maintain consistently.
Should savings be included in a family budget?
Yes. Savings should be a planned part of the budget rather than whatever remains at the end of the month.
How can I budget with an irregular income?
Build your regular lifestyle around a conservative income estimate rather than your best month. When you earn more, consider using the additional money for savings, debt repayment, investments or upcoming expenses.
What should I do if my expenses are higher than my income?
First separate essential expenses from discretionary expenses and list all debt payments. Then look at expenses that can realistically be reduced, review your debt and consider whether increasing income is necessary. If debt has become unmanageable, budgeting alone may not solve the problem.
Is the 50/30/20 rule suitable for Indian families?
It can be a useful starting point, but it isn’t suitable for every household. Indian families have different housing costs, education expenses, family responsibilities, debt levels and incomes.
Should a family have a joint bank account?
Not necessarily. Couples can manage family finances through joint accounts, separate accounts or a combination. The important thing is transparency about household income, expenses, debt and financial goals.
How often should a family review its budget?
A monthly review is usually enough. Take a short look at your spending at the end of each month and adjust the following month’s budget based on what actually happened.
Final Thought
A family budget isn’t about asking:
“How can we spend as little as possible?”
A better question is:
“How should we use the money our family has?”
Once you know what it costs to run your home, how much debt you have, what you need for emergencies, what you want to build for the future and how much you can comfortably spend today, money becomes easier to manage.
You may not be able to control every expense.
But you can give your money a direction.
And that is what a good family budget is really for.