When you invest in a mutual fund, you may notice that the same scheme is available in two versions:
Direct Plan and Regular Plan.
This can be confusing, especially if you’re a beginner.
You might see the same fund name, the same fund manager and broadly the same portfolio. So naturally, you may wonder:
What is the difference between direct and regular mutual fund plans?
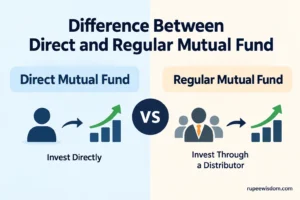
The main difference is simple: a direct plan is bought without a mutual fund distributor, while a regular plan is bought through a distributor or intermediary.
If you’re completely new to mutual funds, it may help to first understand how they work, what you actually own, NAV, SIPs and the different types of funds. Read our beginner-friendly guide on What Is a Mutual Fund? A Simple Beginner’s Guide for Indians
Because of this, the two plans generally have different expense ratios. Direct plans usually have lower expenses, which can give them a cost advantage over the long term.
But that doesn’t mean you should automatically choose direct.
A regular plan can make sense for an investor who values assistance and is comfortable paying for it.
Let’s understand the difference properly before you decide.
Direct vs Regular Mutual Fund: The Basic Difference
Here’s the easiest way to understand it.
Imagine you want to invest ₹5,000 in a particular mutual fund scheme.
You have two routes.
With a direct plan, you invest without a distributor.
With a regular plan, you invest through a distributor or intermediary.
The underlying scheme can be the same.
The portfolio can be the same.
The fund manager can be the same.
But the cost structure is different.
That difference in cost can affect your investment’s value over time.
So, if you’re looking for the difference between direct and regular mutual fund plans in one sentence:
They can invest in the same scheme, but the route of investment and the expenses are different.
What Is a Direct Mutual Fund Plan?
A direct plan allows you to invest in a mutual fund scheme without going through a distributor.
You can invest directly through the fund house or through an investment platform that offers direct plans.
Because there is no distributor involved in the investment route, there is no distributor-related cost in the plan’s expense structure.
As a result, the expense ratio of a direct plan is generally lower than the corresponding regular plan.
For example, you might see a fund listed as:
ABC Equity Fund – Direct Plan – Growth
The word “Direct” indicates that you are investing in the direct plan.
But don’t make the mistake of thinking that “direct” means it is a completely different mutual fund.
If you’re comparing the direct and regular versions of the same scheme, the underlying portfolio and fund manager are generally the same.
The main difference is the distribution route and cost.
What Is a Regular Mutual Fund Plan?
A regular plan is purchased through a mutual fund distributor or intermediary.
The intermediary may help with the investment process and may provide other assistance depending on the service offered.
The distributor is compensated through the distribution arrangement associated with the regular plan.
This is reflected in the plan’s expenses.
As a result, a regular plan generally has a higher expense ratio than the corresponding direct plan.
Again, this doesn’t mean you’re getting a different portfolio.
You’re generally investing in the same underlying scheme.
The difference is that someone is involved in distributing the product, and that distribution has a cost.
Difference Between Direct and Regular Mutual Fund: A Simple Comparison
| Feature | Direct Plan | Regular Plan |
|---|---|---|
| Distributor involved | No | Yes |
| Underlying scheme | Same corresponding scheme | Same corresponding scheme |
| Fund manager | Generally the same | Generally the same |
| Expense ratio | Generally lower | Generally higher |
| NAV | Generally higher | Generally lower |
| Investor involvement | More self-directed | More assisted |
| Distributor assistance | No distributor | May be available |
| Long-term cost | Generally lower | Generally higher |
| Potential long-term return | Cost advantage | Cost disadvantage from higher expenses |
| Tax treatment | Generally the same for the corresponding scheme | Generally the same for the corresponding scheme |
The table gives you the basic difference between direct and regular mutual fund plans.
But there’s an important question hiding underneath it:
Why does a small difference in expenses matter?
Why Does Direct Mutual Fund Usually Have a Higher Return?
Suppose the direct and regular versions of the same scheme hold the same investments.
Imagine the portfolio earns a particular return before expenses.
Both plans start with essentially the same investment performance.
But the regular plan generally has a higher expense ratio.
That additional cost reduces the return that ultimately remains in the plan.
The difference may look insignificant over one year.
But investing is often a long-term activity.
A small difference in annual expenses can have a bigger impact when it continues for 10, 15 or 20 years.
This is because you are not only losing the additional expense itself. You’re also losing the potential future growth on that money.
That is why direct plans generally have a cost advantage over their corresponding regular plans.
However, don’t interpret this as:
“Direct plans guarantee higher returns.”
They don’t.
The underlying investments can rise or fall, and future returns are not guaranteed.
The advantage comes from the lower cost, not from some special investment strategy available only to direct investors.
A Simple Example of the Cost Difference
Suppose two investors each invest ₹5,000 every month in the same mutual fund scheme.
One chooses the direct plan.
The other chooses the regular plan.
Both plans invest in the same underlying portfolio.
Now suppose the regular plan’s expenses are higher.
The difference may seem tiny when you look at one month’s investment.
But imagine that difference continuing for 20 years.
The money paid through additional expenses is money that is no longer invested.
And money that isn’t invested cannot compound for you.
This is why investors should not dismiss expense ratios simply because the difference looks small.
At the same time, don’t assume that a particular percentage difference will always produce a specific rupee difference in your final wealth. The actual outcome depends on the investment amount, returns, expenses and time period.
Why Do Regular Plans Exist If Direct Plans Cost Less?
This is where the conversation often becomes too simplistic.
You will find plenty of articles saying:
“Direct plans are cheaper, so direct plans are better.”
That’s only part of the story.
Some investors are comfortable researching mutual funds, comparing schemes and managing their investments themselves.
Others aren’t.
A new investor may not know:
- what type of fund to consider;
- how much risk a particular fund carries;
- whether several funds in their portfolio are investing in similar companies;
- how to interpret fund information;
- what to do when markets fall sharply;
- whether their investment choices are consistent with their goals.
Some investors prefer having an intermediary involved.
That service has a cost.
So the better question isn’t simply:
“Which one is cheaper?”
It’s:
“Do I need the service I’m paying for?”
That is a much more useful question.
Who May Prefer a Direct Plan?
A direct plan may be suitable for an investor who is comfortable managing their investments independently.
For example, you may prefer a direct plan if you:
- understand basic mutual fund concepts;
- are comfortable researching schemes;
- can compare costs and risks;
- are willing to monitor your investments;
- don’t need assistance from a distributor;
- can stay disciplined when markets become volatile.
You don’t have to be an investment expert.
But you should be willing to learn enough to understand what you’re buying.
Choosing direct doesn’t make someone a smarter investor.
It simply means they’re choosing a more self-directed route.
Who May Prefer a Regular Plan?
A regular plan may suit someone who values assistance from a distributor or intermediary.
Perhaps you’re new to investing.
Perhaps you don’t have the time or confidence to research everything yourself.
Perhaps you simply prefer having someone help you with the investment process.
If the service is genuinely useful to you, paying for it isn’t necessarily a bad thing.
The important part is knowing that you’re paying for that route.
The problem isn’t necessarily the higher expense.
The problem is paying a higher expense without understanding why.
Does Direct Mean You Have to Do Everything Yourself?
Not exactly.
Today, investors have access to plenty of online information, educational resources and investment platforms.
You can research mutual funds, read scheme documents, compare expense ratios and monitor your investments yourself.
But there’s an important distinction between information and personalised advice.
An online article can explain what an expense ratio means.
It cannot automatically tell you whether a particular mutual fund is appropriate for your personal circumstances.
So if you choose a direct plan, understand that you’re taking greater responsibility for your own investment decisions.
Do Direct and Regular Plans Have the Same Fund Manager?
Generally, yes, when you compare the direct and regular versions of the same scheme.
You aren’t getting a different fund manager just because you selected regular.
You also aren’t getting a special portfolio because you selected direct.
The underlying investments are generally the same.
The difference lies primarily in the way the investment is distributed and the expenses associated with that distribution.
This is why the two plans can have different NAVs and different returns even though they invest in the same portfolio.
Why Is the NAV of a Direct Plan Usually Higher?
This confuses many first-time investors.
Suppose you see:
Direct Plan NAV: ₹150
Regular Plan NAV: ₹140
You might think:
“The regular plan is cheaper because its NAV is lower.”
That’s incorrect.
NAV is the value of one unit.
The lower NAV does not mean that you’re getting a bargain.
Because the direct plan generally has lower expenses, its NAV can gradually move ahead of the regular plan’s NAV over time.
So don’t choose between direct and regular based on which one has the lower NAV.
Look at the expense ratio, investment objective, risks and overall structure instead.
Direct vs Regular Is Not the Same as Growth vs IDCW
There is another distinction worth understanding.
When looking at mutual funds, you may see terms such as:
- Direct Growth
- Direct IDCW
- Regular Growth
- Regular IDCW
These describe different things.
Direct vs Regular tells you about the distribution route.
Growth vs IDCW relates to how income/distributions are handled under the applicable scheme structure.
So you shouldn’t think:
Direct = Growth
or
Regular = IDCW
They are separate choices.
A fund can have both direct and regular plans, and each may have different options.
Is SIP Direct or Regular?
SIP is another thing beginners frequently mix up.
SIP is not a separate type of mutual fund.
It is a method of investing a fixed amount at regular intervals.
You can generally invest through a SIP in either a direct or regular plan.
So:
Direct vs Regular = investment route
SIP = investment method
For example:
₹5,000 every month into a direct mutual fund plan through SIP.
That’s a perfectly normal way of describing the investment.
Can You Invest in a Direct Plan Through an App?
Yes.
The word “direct” doesn’t mean that you have to visit the mutual fund company’s office.
Several investment platforms allow investors to select direct mutual fund plans.
But don’t assume that every investment option displayed on an app is automatically a direct plan.
Always check the exact plan name.
You might see:
ABC Equity Fund – Direct – Growth
and
ABC Equity Fund – Regular – Growth
Make sure you know which one you’re selecting before completing the investment.
Does a Direct Plan Need a Demat Account?
Not necessarily.
You can invest in mutual funds without necessarily having a demat account, depending on the investment route you use.
A demat account is generally associated with holding securities such as shares and certain exchange-traded investments.
So don’t assume:
“I don’t have a demat account, therefore I can’t invest in a direct mutual fund.”
You can explore eligible routes that don’t require one.
Do Direct and Regular Mutual Funds Have Different Tax Treatment?
Generally, the corresponding direct and regular plans of the same mutual fund scheme are not taxed differently simply because one is direct and the other is regular.
Tax treatment depends on factors such as the type of mutual fund, the nature and timing of the transaction and the tax rules applicable at the time.
So taxation should not be the main reason for choosing direct over regular.
The more important difference is the expense structure and distribution route.
Tax rules can change, so check the current rules before making a transaction based on tax considerations.
Can You Switch From a Regular Plan to a Direct Plan?
Yes, but don’t treat it as a simple change of settings.
Moving from a regular plan to a direct plan can involve redeeming your existing units and investing in the direct plan.
Depending on your circumstances, this may have consequences such as:
- Capital gains taxation
- Exit load, if applicable
- Change in the number of units
- Transaction-related considerations
For example, if you’ve held your existing investment for several years and it has appreciated substantially, selling it simply to move to a direct plan could have tax implications.
So don’t switch merely because someone says:
“Direct is always better.”
First calculate what you’re actually saving in expenses and compare that with the costs and consequences of making the switch.
Is Direct Always Better Than Regular?
If you’re comparing only the expense ratio, the direct plan generally has the advantage.
But investment decisions shouldn’t be based on one number alone.
Imagine two investors.
Investor A chooses a direct plan because it is cheaper, but doesn’t understand the funds, keeps changing investments and sells in panic whenever markets fall.
Investor B chooses a regular plan, understands the costs, receives useful assistance and remains disciplined.
Simply knowing that Investor A chose direct doesn’t tell us who will have the better investment outcome.
The lower cost of a direct plan is a genuine advantage.
But your behaviour, the investment itself and the quality of the decisions you make matter too.
That’s why “direct is always better” is too simplistic.
How Should a Beginner Decide Between Direct and Regular?
Instead of asking somebody which one you should choose, ask yourself these questions.
Do I understand what I’m investing in?
If not, learn first.
Don’t choose direct simply because it has a lower expense ratio.
Am I comfortable researching mutual funds?
If you enjoy doing your own research and understanding fund information, direct may be worth considering.
Do I value the assistance of a distributor?
If you genuinely use and value the service, a regular plan may make sense.
Do I know what I’m paying?
This is essential.
Before investing in a regular plan, understand the difference in expense ratio and what you’re getting in return for the additional cost.
Am I considering switching an existing investment?
Don’t look only at the future expense savings.
Check possible capital gains tax, exit load and other consequences before making the move.
The Biggest Mistake Is Choosing the Wrong Fund, Not Just the Wrong Plan
Here’s something I’d like beginners to remember.
People sometimes spend hours arguing about:
Direct or regular?
while completely ignoring the much bigger question:
What mutual fund am I actually investing in?
A low-cost direct plan doesn’t automatically make a poor investment into a good one.
You could choose the cheapest plan available and still invest in a fund that doesn’t match your objective, time horizon or risk tolerance.
So the order should be:
Understand your financial goal
↓
Understand the type of investment
↓
Understand the mutual fund scheme
↓
Understand the risks and costs
↓
Then decide between direct and regular
That’s a much healthier approach.
Difference Between Direct and Regular Mutual Fund: The Bottom Line
The difference between direct and regular mutual fund plans is primarily about how you invest and what you pay for that route.
A direct plan is purchased without a distributor and generally has a lower expense ratio.
A regular plan is purchased through a distributor or intermediary and generally has a higher expense ratio because of the distribution arrangement.
When comparing the corresponding direct and regular versions of the same scheme, the underlying portfolio and fund manager are generally the same.
So why does the distinction matter?
Because costs matter over long periods.
A higher expense ratio can gradually reduce the amount of money that remains invested and compounds for you.
But that doesn’t mean every investor should immediately move to direct plans.
If you are comfortable researching and managing your own investments, the lower cost of a direct plan may be attractive.
If you genuinely value assistance from a distributor and are comfortable paying for that service, a regular plan may be reasonable.
The key is to know what you’re paying for and why.
For more information on mutual fund plans and how they work, you can also refer to the SEBI Investor guide on mutual funds
Don’t choose direct because somebody says it’s automatically better.
Don’t choose regular simply because someone offers it to you.
First understand the difference.
Then look at the mutual fund itself.
And only after that decide which route makes sense for you.
Frequently Asked Questions
What is the difference between direct and regular mutual fund plans?
A direct plan is purchased without a distributor, while a regular plan is purchased through a distributor or intermediary. Direct plans generally have lower expense ratios, while regular plans generally have higher expenses because of the distribution arrangement.
Which is better, direct or regular mutual fund?
Neither is universally better. A direct plan may suit investors who are comfortable managing their investments themselves. A regular plan may suit investors who value assistance from a distributor or intermediary.
Do direct and regular plans have the same portfolio?
When comparing the corresponding direct and regular versions of the same scheme, they generally have the same underlying portfolio and fund manager.
Why is the NAV of a direct plan usually higher?
Direct plans generally have lower expenses. Over time, this cost difference can contribute to the direct plan having a higher NAV than the corresponding regular plan.
Does a direct mutual fund give higher returns?
A direct plan generally has a lower expense ratio, which gives it a cost advantage over the corresponding regular plan. This can result in higher returns over time, all else being equal. It does not guarantee higher future returns.
Can I change from regular to direct?
Yes, but moving from one plan to another can involve a redemption and a fresh investment. Capital gains tax, exit load and other consequences may apply depending on the circumstances.
Is SIP direct or regular?
SIP is a method of investing regularly. You can generally use a SIP to invest in either a direct or regular mutual fund plan.
Do I need a demat account for a direct mutual fund?
Not necessarily. Mutual funds can generally be invested in through routes that do not require a demat account.
Are direct and regular plans taxed differently?
Generally, corresponding direct and regular plans of the same scheme are not taxed differently simply because one is direct and the other is regular. Applicable taxation depends on the type of fund and prevailing tax rules.
Does regular mean I get financial advice?
Not necessarily. A regular plan involves a distributor or intermediary, but the nature and extent of assistance provided can vary. Understand what service you’re receiving and what you’re paying for it.